Getting Expert Help
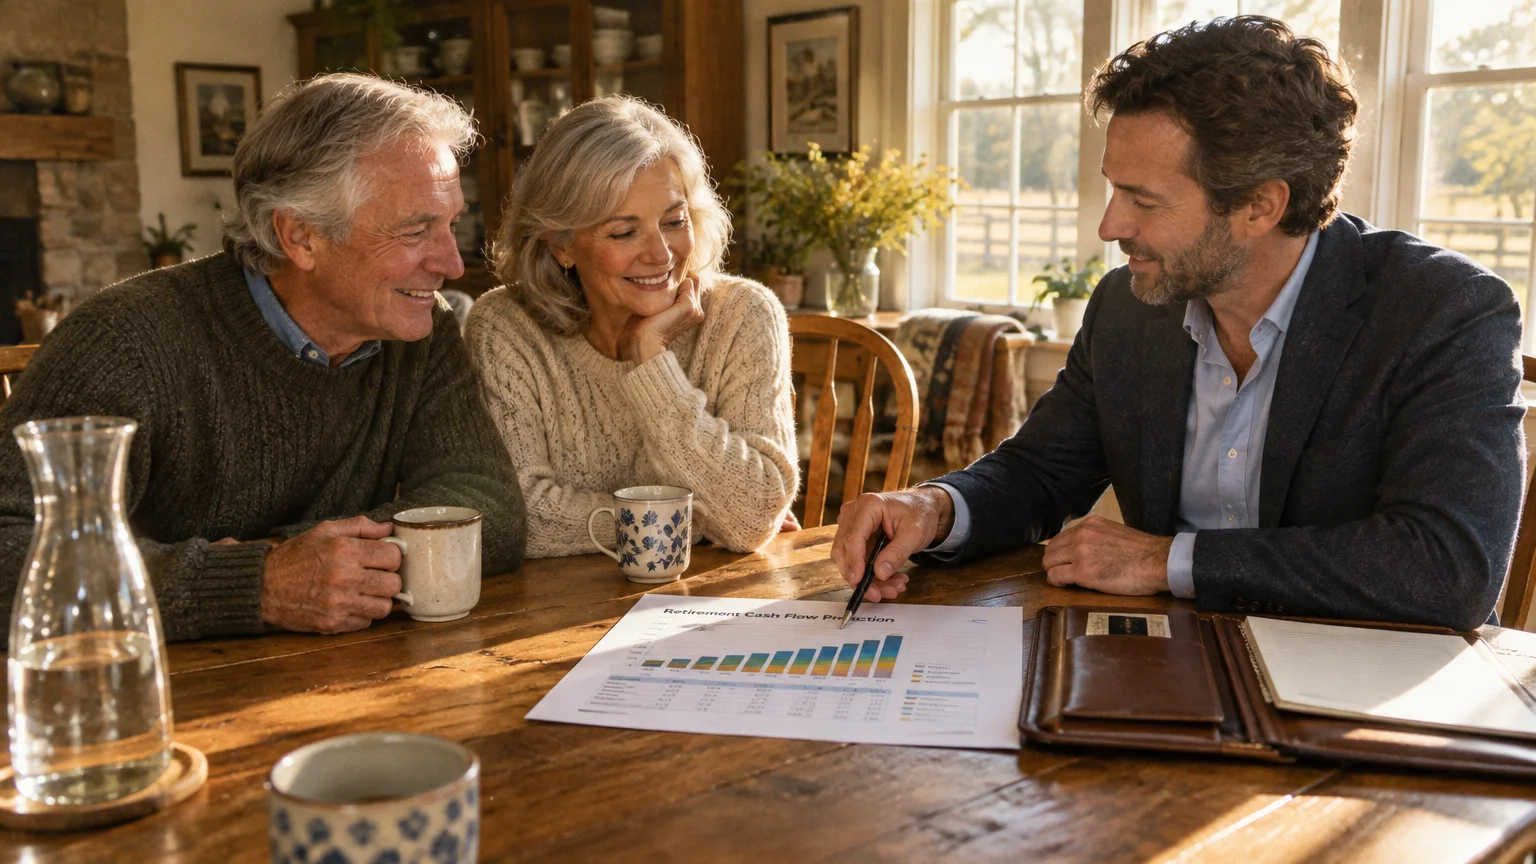
While casual online gigs are straightforward, managing self-employment income alongside retirement pensions requires thoughtful financial coordination. Professional guidance helps you preserve your wealth and optimize your tax returns.
Consult a Certified Public Accountant (CPA) if your freelance revenue pushes your total household income into a higher federal tax bracket. A tax professional can help you deduct legitimate expenses like home internet, office supplies, and computer equipment.
Speak with a Certified Financial Planner (CFP) if your combined income risks raising your Medicare Part B or Part D premiums through Income-Related Monthly Adjustment Amounts (IRMAA). A planner can balance remote earnings against retirement account withdrawals.
Contact your local Social Security field office if you work before reaching Full Retirement Age. Reporting your anticipated earnings in advance prevents the agency from issuing stressful benefit overpayment notices later.
I am looking for regular part-time remote work in the legal field.
I would like more information on this job.