Retired in USA

Your golden years are your best years! Make them shine!

  • Home
  • Personal Finance
  • Retirement Life
  • Saving & Spending

HSAs Sound Great – Until You See These 3 Hidden Costs

February 8, 2026 · Personal Finance

You’ve likely heard the Health Savings Account (HSA) described as the ultimate retirement vehicle. Financial experts often call it the “triple threat” of investing: tax-free contributions, tax-free growth, and tax-free withdrawals for qualified medical expenses. For many, it effectively beats a 401(k) or IRA because it’s the only account that can be completely tax-free from start to finish.

But there is a catch. Actually, there are three.

While the benefits of an HSA are undeniable, the “perfect” retirement account has some serious flaws that rarely make the headlines. If you aren’t careful, these hidden pitfalls can trigger unexpected tax bills, erode your investment returns, or leave your heirs with a massive financial burden.

Here is the reality of HSAs that most brochures won’t tell you—and how you can navigate these traps to keep your retirement savings safe.

The Essentials: What You Need to Know

  • The Medicare Trap: Contributing to an HSA while enrolled in Medicare (even retroactively) triggers IRS penalties.
  • The Inheritance Bomb: Unlike an IRA, an HSA left to a non-spouse beneficiary is fully taxable in a single year.
  • The “Cash Drag”: High fees and mandatory cash minimums can silently eat away at your long-term compound growth.
  • 2025/2026 Limits: For 2025, you can contribute up to $4,300 (self) or $8,550 (family). These limits rise to $4,400 and $8,750 in 2026.
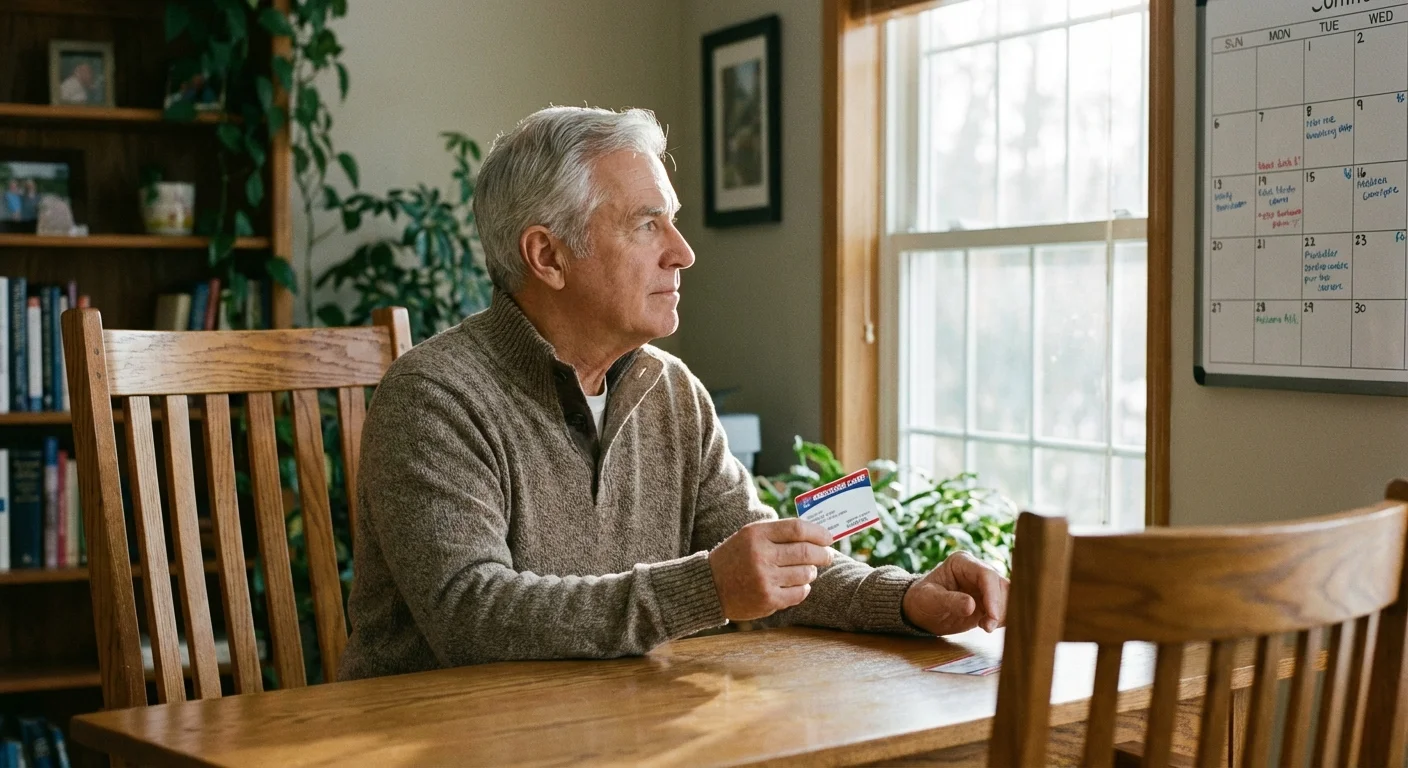
A man looking at a calendar and a Medicare card at a wooden desk.
A pensive senior man holds his Medicare card, looking out the window while considering the financial risks of benefit clawbacks.

1. The Medicare “Clawback” Trap

The most dangerous hidden cost for retirees involves the transition to Medicare. Many seniors assume they can keep contributing to their HSA as long as they are working, even if they are approaching age 65. This assumption can lead to a messy tax situation.

Here is the rule: You cannot contribute to an HSA once you are enrolled in any part of Medicare (Part A or Part B).

The problem arises because most people don’t realize when their Medicare coverage actually begins. If you apply for Social Security at age 65 or later, you are automatically enrolled in Medicare Part A. More importantly, your Part A coverage is often retroactive for up to six months.

How the 6-Month Lookback Rule Burns You

If you retire at age 67 and apply for Social Security or Medicare, your Part A coverage will likely be backdated by six months to ensure you have no coverage gaps. The IRS considers you “enrolled” in Medicare during those six retroactive months.

If you made HSA contributions during that six-month window, the IRS considers them “excess contributions.” You will face:

  • Income Tax: You must add those contributions back to your taxable income.
  • 6% Excise Tax: You will pay a 6% penalty on the excess amount for every year it remains in the account.

The Fix: If you plan to enroll in Medicare or Social Security after age 65, stop all HSA contributions six months before your application date. This creates a safety buffer that prevents the retroactive coverage from overlapping with your contributions.
Pages: 1 2 3 4 5

Share this article

Facebook Twitter Pinterest LinkedIn Email

Leave a Reply Cancel reply

Your email address will not be published. Required fields are marked *

Search

Latest Posts

  • Senior couple sitting at a wooden kitchen table reviewing paper receipts, bank statements, and store reward cards. 9 Store Membership Tiers That Are Rarely Worth the Upgrade
  • Senior couple sitting at a wooden table reviewing Social Security and Medicare documents beside a budget notepad. 10 Things Nobody Explains About Medicare's Late Enrollment Penalty
  • An older man sits at a dining table with a laptop, ledger, and banking statements from multiple financial institutions. 8 Reasons Retirees Are Splitting Their Savings Across More Banks
  • A senior man sits at a wooden table reviewing financial papers with a calculator, eyeglasses, and coffee mug nearby. 9 Things That Happen to Debt When You Retire With It
  • A woman reviews Medicare Advantage comparison guides and plan documents at a wooden table with a coffee cup. 10 Things Nobody Explains About Medicare Advantage Switching
  • Mature couple reviewing retirement portfolio charts and taking notes at a sunlit wooden kitchen table with a laptop. 8 Reasons Retirees Are Rethinking the 4% Withdrawal Rule
  • An older woman in an apron waters potted plants on a sunny front porch with a small dog lying beside her. 12 States Where a Modest Pension Still Goes a Long Way
  • Older couple relaxing in wooden chairs on a porch with coffee mugs and a newspaper on a rustic wooden table. 12 Places Where Property Taxes Are Basically Nonexistent for Retirees
  • An older couple holding mugs on a wooden balcony overlooking a misty valley town and distant mountains at sunrise. 11 Places Retirees Keep Naming as Their Biggest Surprise Favorite
  • Mature woman sitting at a sunlit wooden table reviewing paperwork, with eyeglasses, a pen, and a steaming mug nearby. 15 Financial Challenges Widowed Spouses Often Don't See Coming

Newsletter

Get retirement tips and senior living advice delivered to your inbox.

Related Articles

funeral expenses

Funeral Expenses: 5 Best Ways to Lower Them

We bet you never considered you can save when it comes to funeral expenses! Have…

Read More →
Illustration of a senior woman planning her budget at a sunlit table, symbolizing retirement financial planning.

What a Higher COLA Could Mean for Your Budget

Discover how the 2026 Social Security COLA increase impacts your retirement budget, including crucial offsets…

Read More →
Mature woman sitting at a sunlit wooden table reviewing paperwork, with eyeglasses, a pen, and a steaming mug nearby.

15 Financial Challenges Widowed Spouses Often Don’t See Coming

Learn 15 unexpected financial challenges widowed spouses face, from the widow's tax penalty and Social…

Read More →
working in retirement, tax change

The ONLY Unexpected Tax Change Seniors Will Face in 2025

A senior man thoughtfully reviews financial paperwork in his library, preparing for the significant tax…

Read More →
An older woman reviewing a Social Security Administration letter at her kitchen table with a magnifying glass and a calculator.

Why Retirees Are Watching COLA Estimates Closely

Discover how the latest COLA estimates and rising Medicare premiums impact your Social Security benefits,…

Read More →
Senior Housing, everyday bill

Watch Out: 8 Everyday Bills That Lead to Financial Strain

A woman thoughtfully reviews a stack of bills with a calculator, carefully managing the impact…

Read More →
financial stability in retirement

6 Finance Tips to NEVER Ask Your Kids for Money Again

Most of us strive to achieve financial stability in retirement, but this is not always…

Read More →
An editorial gouache illustration of a scale tipped by a single dollar coin, representing the IRMAA threshold.

The Retirement Income Trap That Pushes You Into a Higher IRMAA Bracket

Learn how to avoid Medicare IRMAA surcharges, navigate income traps like RMDs and municipal bonds,…

Read More →
Illustration of a retired couple looking at a calendar and a compounding growth chart labeled COLA Base.

6 Ways to Boost Your Next COLA Check

Learn 6 practical ways to maximize your Social Security COLA check by increasing your primary…

Read More →
Retired in USA

Your golden years are your best years! Make them shine!

Inedit Agency S.R.L.
Bucharest, Romania

contact@ineditagency.com

Trust & Legal

  • Contact
  • Editorial Policy
  • Advertiser Disclosure
  • FAQ
  • Subscribe
  • Unsubscribe
  • Privacy Policy
  • Terms and Conditions
  • Disclaimer
  • Do not sell my personal information
  • Request to Know
  • Request to Delete
  • CA Privacy Policy

Categories

  • Enjoying Retirement
  • Personal Finance
  • Saving & Spending

© 2026 Retired in USA. All rights reserved.