A modest pension or monthly Social Security benefit can easily fund a debt-free retirement when you choose the right location. Strategic geographic moves eliminate mortgage pressure and keep your essential living expenses beneath your guaranteed income.
In 2026, the average retired worker collects roughly $2,000 each month in baseline benefits. While high-cost cities swallow that sum immediately, affordable destinations allow you to live comfortably without borrowing a dime.
Whether you settle in quiet American towns with negligible taxes or scenic overseas havens, true financial peace is achievable. Explore these 12 proven locations where your fixed income buys total independence.
Understanding the Debt-Free Pension Math
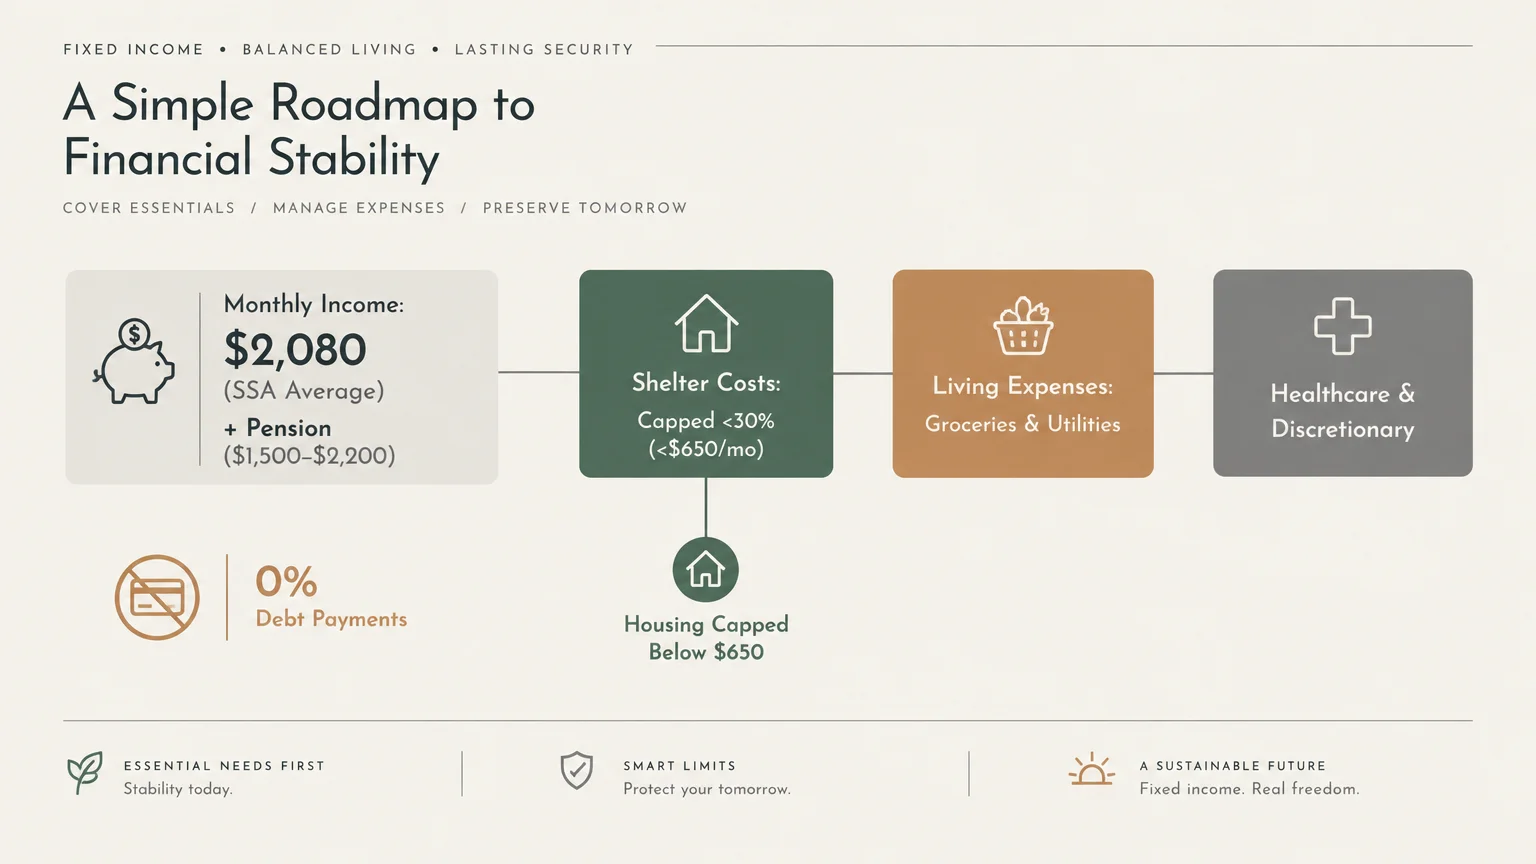
A small pension generally falls between $1,500 and $2,200 per month. Living debt-free on this sum means eliminating mortgages, auto loans, and high-interest revolving balances.
According to data from the Social Security Administration, the typical retired worker receives about $2,080 monthly in 2026. Pairing that payment with a modest private pension unlocks genuine comfort in low-overhead regions.
Your primary objective is capping total shelter costs below 30% of your income. When housing takes less than $650 per month, your remaining funds easily cover groceries, utilities, and healthcare.
“Living within your means is the single greatest stress reliever in retirement.” — Jean Chatzky, Financial Educator and Author
6 Low-Cost U.S. Destinations for Pensioners
Staying within the United States allows you to keep Medicare benefits intact while maintaining geographic proximity to family. These six domestic markets deliver remarkable housing values and favorable retiree tax policies.
1. Bluefield, West Virginia
Bluefield sits in the Appalachian Mountains and provides some of the lowest property values in the nation. Median home prices consistently hover around $100,000, while quality one-bedroom apartments rent for under $650 monthly.
As of January 1, 2026, West Virginia completed the full phaseout of its state income tax on Social Security. You keep every dollar of your federal benefits while enjoying four mild mountain seasons.
2. Hattiesburg, Mississippi
Hattiesburg combines vibrant university town amenities with exceptionally cheap housing. Local single-family homes frequently sell under $160,000, creating realistic cash-purchase opportunities for downsizing retirees.
Mississippi completely exempts all qualified retirement income, pensions, and Social Security distributions from state income tax. Furthermore, generous homestead exemptions significantly reduce your annual county property tax liability.
3. Dothan, Alabama
Located near the Florida border, Dothan offers warm weather without coastal price tags. You can easily find modest, move-in-ready brick homes for well under $150,000.
Alabama boasts an effective property tax rate of roughly 0.40%, among the lowest in the country. The state also fully exempts defined-benefit pensions and Social Security from state income taxation.
4. Johnstown, Pennsylvania
Johnstown provides historic brick architecture and deeply discounted residential real estate. Median single-family home prices remain near $110,000, allowing you to acquire a debt-free residence with modest home equity.
Pennsylvania does not tax pension payments, 401(k) withdrawals, or Social Security benefits for retirees aged 60 and older. This generous tax climate preserves your cash flow for daily expenses.
5. Fort Smith, Arkansas
Fort Smith lies along the Arkansas River and features everyday living costs roughly 17% below national averages. Local healthcare networks provide comprehensive clinical care at affordable co-pay rates.
Arkansas completely exempts Social Security payments and provides an additional exclusion on up to $6,000 of other retirement benefits. You can comfortably maintain a one-bedroom rental here for $700 per month.
6. Terre Haute, Indiana
Terre Haute offers quiet Midwestern living with outstanding access to regional medical centers. Modest two-bedroom starter homes trade between $115,000 and $135,000 across stable residential neighborhoods.
Utility costs and property taxes run well below national baselines. A thrifty single retiree can manage a complete monthly budget here on approximately $1,600 to $1,800.
6 Overseas Havens Accessible on a Small Pension
Moving abroad can stretch a small dollar pension into an upper-middle-class lifestyle. However, you must select countries with realistic statutory income thresholds for legal retiree residency.
Many popular destinations have raised financial solvency bars significantly. For instance, Mexico’s temporary residency now requires over $4,100 per month in income, placing it out of reach for modest pensions.
The six destinations below maintain formal pension visas that welcome retirees earning under $2,000 each month.
7. Boquete, Panama
Boquete is a mountain enclave famous for its perpetual spring climate and established expat community. The Panamanian Pensionado visa requires only a lifetime pension of $1,000 per month.
If you purchase titled real estate valued at $100,000 or more, Panama reduces that pension requirement to $750 monthly. The program also grants statutory discounts, including 20% off medical consultations and 25% off restaurant meals.
8. Atenas, Costa Rica
Atenas sits in Costa Rica’s Central Valley, where temperate breezes eliminate the need for air conditioning or home heating. The national Pensionado program requires proof of a lifetime pension of $1,000 per month.
Foreign pensions remain completely exempt from local income taxes. You gain access to the universal Caja public healthcare system for an affordable monthly contribution pegged to your declared income.
9. Dumaguete, Philippines
Dumaguete is a coastal university city known as the “City of Gentle People.” The Philippine Retirement Authority offers the Special Resident Retiree’s Visa (SRRV) Classic to pension-holding applicants aged 50 and older.
You only need to show an $800 monthly pension and place a qualifying $15,000 deposit in a local bank. English is spoken everywhere, and comfortable coastal rentals cost under $400 each month.
10. Manizales, Colombia
Manizales nestles in Colombia’s lush coffee axis, delivering modern infrastructure and superb hospital care. The Migrante M-Pensionado visa requires proof of monthly pension income equal to three times the national minimum wage.
In 2026, this threshold equals roughly $1,350 to $1,450 per month, depending on exchange rates. Furnished high-rise apartments in upscale neighborhoods rent for under $550 monthly.
11. Chiang Mai, Thailand
Chiang Mai blends ancient culture, world-class private hospitals, and remarkably inexpensive dining. Thailand’s Non-Immigrant retirement visa requires a monthly pension of 65,000 baht (roughly $1,850) or an 800,000-baht bank deposit.
A couple can live in total comfort on $1,600 to $1,900 monthly, including regular dining out and domestic travel. Fresh open-air markets keep your monthly grocery expenses under $250.
12. Cuenca, Ecuador
Cuenca charms retirees with colonial architecture, clean mountain air, and an official U.S. dollar economy. Because Ecuador uses the dollar, you never face foreign exchange fees or currency depreciation risks.
The Ecuadorian Jubilado visa requires a guaranteed monthly pension equal to three national basic salaries, or roughly $1,400 monthly. High-quality public health insurance costs around $90 per month for full coverage.
Cost Comparison Across All 12 Destinations
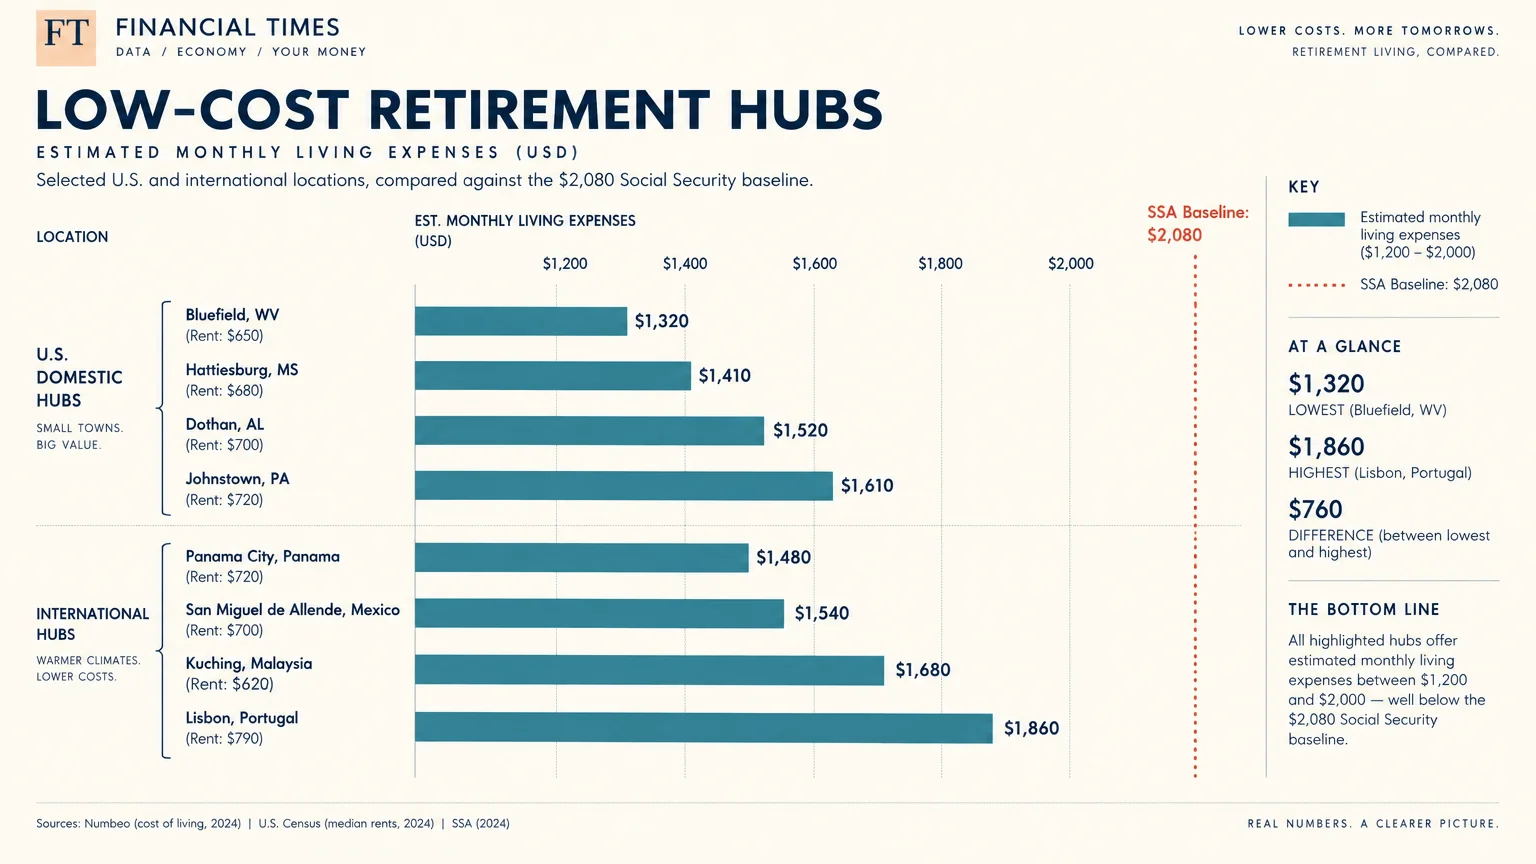
Reviewing baseline costs clarifies how each destination fits your specific pension payment. The figures below reflect typical monthly living expenses for a single retiree living debt-free.
| Destination | Location Type | Est. Monthly Budget | Typical Shelter Cost | Key Financial Advantage |
|---|---|---|---|---|
| Bluefield, WV | Domestic (U.S.) | $1,500 – $1,750 | $600/mo (Rent) | Full Social Security tax exemption |
| Hattiesburg, MS | Domestic (U.S.) | $1,650 – $1,900 | $750/mo (Rent) | Zero state tax on qualified pensions |
| Dothan, AL | Domestic (U.S.) | $1,600 – $1,850 | $700/mo (Rent) | 0.40% effective property tax rate |
| Johnstown, PA | Domestic (U.S.) | $1,550 – $1,800 | $625/mo (Rent) | Retirement income exempt from state tax |
| Fort Smith, AR | Domestic (U.S.) | $1,650 – $1,900 | $700/mo (Rent) | Low utility and grocery index |
| Terre Haute, IN | Domestic (U.S.) | $1,600 – $1,850 | $675/mo (Rent) | Median home prices under $135,000 |
| Boquete, Panama | International | $1,400 – $1,800 | $550/mo (Furnished) | Statutory discounts up to 50% on services |
| Atenas, Costa Rica | International | $1,500 – $1,900 | $600/mo (Rental) | No income tax on foreign pensions |
| Dumaguete, Philippines | International | $1,100 – $1,400 | $375/mo (Apartment) | Low visa income threshold ($800/mo) |
| Manizales, Colombia | International | $1,200 – $1,550 | $450/mo (High-rise) | Inexpensive Tier-1 hospital care |
| Chiang Mai, Thailand | International | $1,200 – $1,600 | $400/mo (Condo) | World-class dining and low transit costs |
| Cuenca, Ecuador | International | $1,250 – $1,600 | $475/mo (Historic) | U.S. Dollar currency; $90/mo public care |
Actionable Steps to Retire Debt-Free on a Small Budget
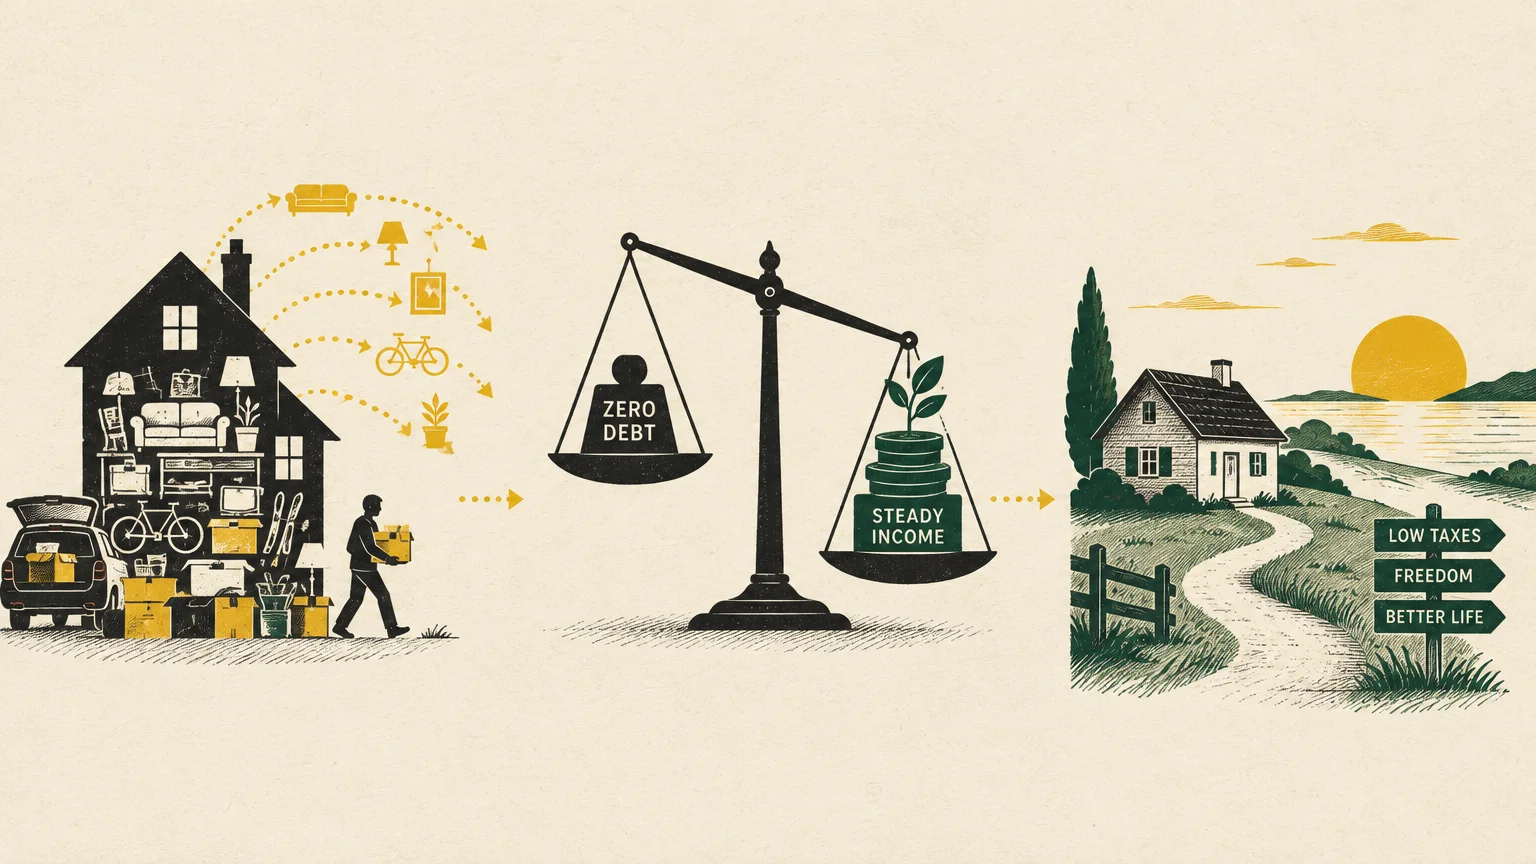
Moving to an inexpensive location solves only half of the retirement puzzle. You must also implement disciplined debt-reduction practices before unpacking your boxes.
- Liquidate Consumer Debt First: Clear all revolving balances and auto notes before moving. Review guidance from the Consumer Financial Protection Bureau to build a structured debt payoff plan.
- Downsize Square Footage: Transition into a small single-story residence or rental. Smaller footprints dramatically slash utility, maintenance, and insurance outlays.
- Lock in Fixed Housing Costs: Purchase an affordable home with cash or secure long-term rental leases with predictable annual escalation caps.
- Audit Healthcare Options: Confirm whether local medical facilities accept your coverage. If remaining in the U.S., review your choices on Medicare.gov during Open Enrollment.
Eliminating loan obligations gives you total control over your monthly cash flow. When you owe nothing to lenders, a $1,800 pension provides genuine autonomy.
“Debt is a trap that steals your future margin. When you remove payments from the equation, even a modest check provides enormous freedom.” — Dave Ramsey, Personal Finance Author
What Can Go Wrong (And How to Protect Yourself)
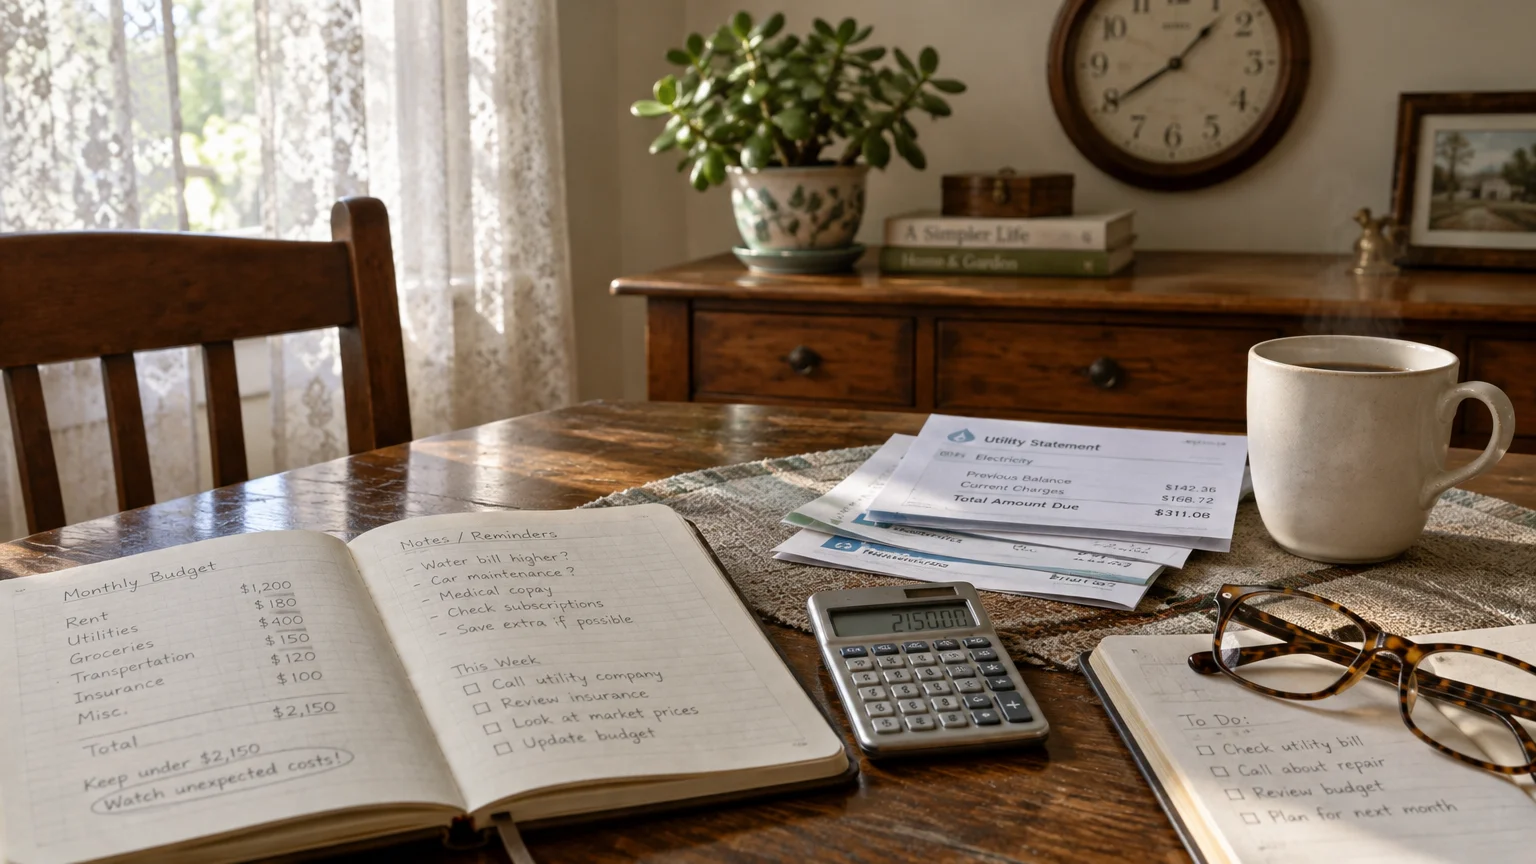
Relocating on a fixed income involves practical hazards that can quickly strain your monthly budget. Preparing for these risks protects your long-term solvency.
International retirees often forget that Medicare does not cover medical treatment outside American borders. You must budget for private international health insurance or enroll in the host country’s public healthcare system.
Currency fluctuations can also erode your purchasing power in non-dollarized foreign countries. Keeping several months of living expenses in an emergency fund prevents forced currency conversions during unfavorable market swings.
For domestic moves, property taxes can jump after local assessors re-evaluate your newly purchased home. Always verify senior property tax exemptions directly with county assessment offices before completing a real estate transaction.
Federal tax filing obligations continue regardless of where you reside globally. Consult the Internal Revenue Service to understand foreign income reporting and filing requirements for expats.
When to Consult a Professional
Relocation decisions create ripple effects across your taxes, estate plans, and healthcare coverage. Consider meeting with a fee-only advisor under these specific circumstances:
- Cross-Border Tax Planning: Navigating dual-country tax treaties and Foreign Bank Account Reporting (FBAR) rules requires specialized international CPA guidance.
- Real Estate Liquidation: Selling your existing primary residence to fund a cash purchase in a lower-cost market triggers capital gains questions that demand tax analysis.
- Medicare Part B Decisions: If moving abroad temporarily, suspending or retaining Medicare Part B requires professional evaluation to avoid lifetime late-enrollment penalties.
Frequently Asked Questions
Can you really live on a $1,500 monthly pension in the United States?
Yes, you can live comfortably on $1,500 per month if you own your home outright or rent in low-cost markets like Johnstown or Bluefield. Controlling your housing expense is the essential key.
Does Medicare cover me if I retire to an international destination?
Medicare does not cover healthcare services received outside the United States and its territories. You must purchase private international insurance or enroll in your host country’s resident health program.
Why is Mexico excluded from this list of low-pension destinations?
Mexico updated its residency requirements to multiples of its rising daily minimum wage. In 2026, qualifying for Mexican temporary residency requires monthly income exceeding $4,100, locking out small pensions.
Do states tax out-of-state public or private pensions?
State tax treatment varies widely. States like Mississippi and Pennsylvania completely exempt qualified pension income, while others tax pensions as ordinary income once you exceed specific age or dollar thresholds.
Taking Your Next Steps
Living debt-free on a modest pension does not require extreme sacrifice; it requires thoughtful geography. Spend time visiting your top candidate towns as a temporary resident before making a permanent commitment.
Focus on shedding consumer debt today so that your retirement income remains entirely yours tomorrow. With deliberate planning, you can build a stable, worry-free retirement regardless of your pension size.
This educational content relies on general retirement planning principles, and individual results vary. Always verify current benefit amounts, tax laws, and visa eligibility with official government sources.
Last updated: February 2026. Retirement benefits, tax laws, and healthcare costs change frequently—verify current details with official sources.