If you feel like your dollar stretches a little less every time you visit the store, the data supports your suspicion. While inflation has cooled in some sectors, specific categories are seeing price surges in 2026 that disproportionately affect retirees. From the coffee in your morning mug to the insurance protecting your home, several key expenses are climbing faster than the average Cost of Living Adjustment (COLA).
Understanding exactly where these increases are hiding is the first step to protecting your retirement budget. This isn’t just about inflation—it’s about supply chain shifts, climate impact on agriculture, and regulatory changes hitting your wallet this year.
Here are six specific products and services costing you more in 2026, along with practical strategies to mitigate the damage.
1. Medicare Part B Premiums
Healthcare is often the single largest expense in retirement, and 2026 brings a notable increase to your standard monthly premiums. While many retirees celebrate the new $2,000 out-of-pocket cap on prescription drugs (Part D), the costs for Part B—which covers doctor visits and outpatient care—have risen.
The 2026 Numbers:
- Standard Part B Premium: Increased to roughly $202.90 per month (up from $185.00 in 2025).
- Part B Deductible: Rose to $283 (an increase of roughly $26).
- Part A Deductible: For hospital stays, the deductible is now roughly $1,736 per benefit period.
Note: If you have a higher income (roughly above $106,000 for individuals or $212,000 for couples), you will pay even more due to IRMAA (Income-Related Monthly Adjustment Amount) surcharges.
What You Can Do
You cannot negotiate the standard Medicare premium, but you can manage your total health spend. First, ensure you are utilizing your preventative benefits; Medicare covers annual wellness visits and screenings at no extra cost. Second, if you are subject to IRMAA surcharges due to a one-time spike in income (like selling a home), you can file an appeal (Form SSA-44) to request a reduction.
2. Morning Staples: Coffee & Chocolate
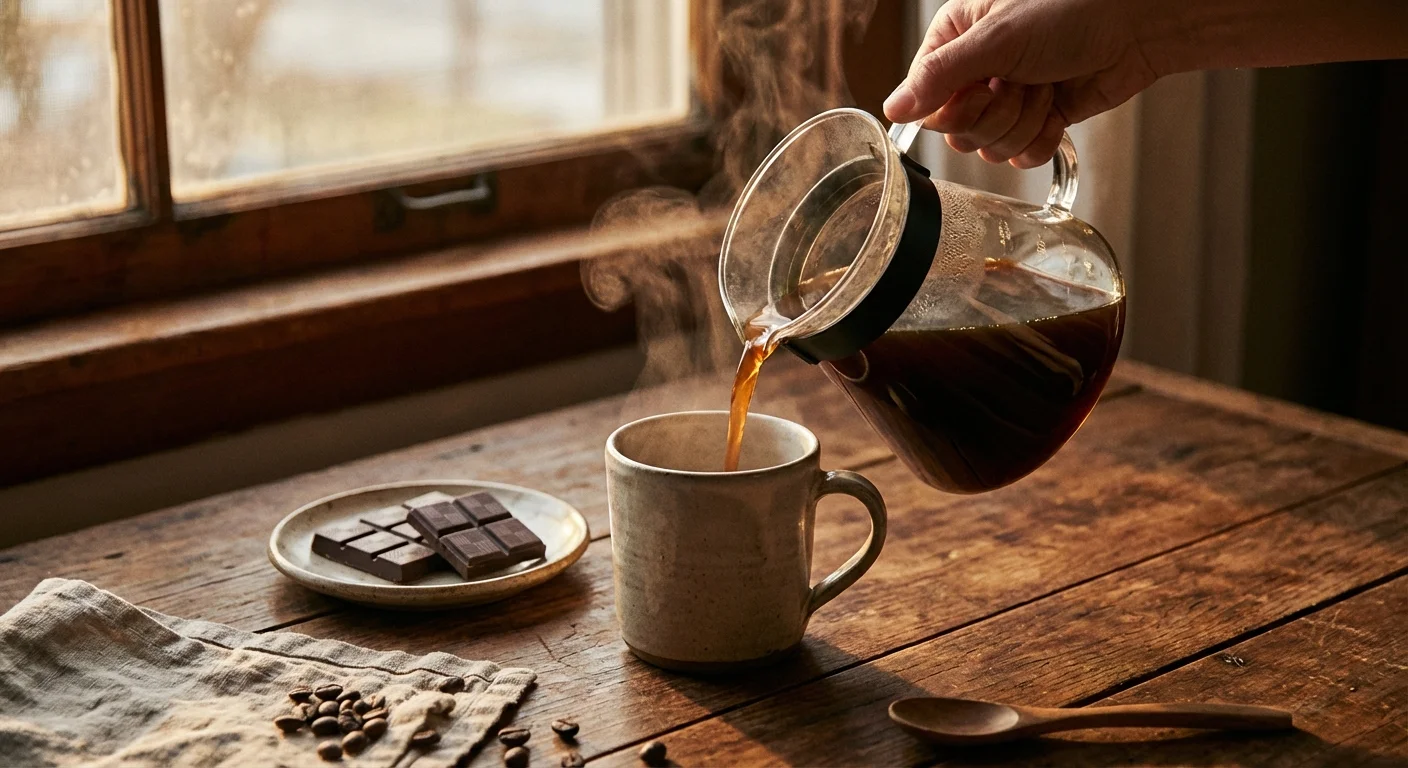
Your grocery bill might look different in 2026, specifically in the “luxury staples” aisle. Agricultural challenges are driving up the cost of two retiree favorites: coffee and chocolate.
Why the Price Hike?
Both coffee beans and cocoa are extremely sensitive to climate patterns. Droughts in Brazil and Vietnam, combined with supply chain bottlenecks, have tightened global supply. Analysts project coffee retail prices could climb significantly in early 2026—some estimates suggest a double-digit percentage increase in the first quarter alone.
Similarly, cocoa prices have remained elevated due to shortages in West Africa. This means that chocolate bars, baking cocoa, and even mocha-flavored treats will carry a higher price tag this year.
Smart Shopping Tips
- Buy Whole Bean in Bulk: Ground coffee degrades faster. Buying whole beans in bulk (3–5 lb bags) from warehouse clubs often yields a lower price per cup and stays fresh longer if stored predominantly in the freezer.
- Switch Brands: If your premium brand hikes prices, consider store brands (private labels). Many obtain beans from the same regions but cost 20–30% less.
- Stock Up on Sales: Unlike perishable produce, vacuum-sealed coffee and dark chocolate have long shelf lives. When you see a “Buy One, Get One” deal, grab a few months’ supply.
3. Homeowners Insurance
If you haven’t opened your insurance renewal letter yet, prepare yourself. Homeowners insurance rates have been skyrocketing, and the trend continues into 2026. This is driven by increased severity of weather events and the rising cost of building materials and labor.
In 2024 alone, rates jumped nearly 17%, and 2026 is seeing further increases as insurers adjust for risk. In some states like Florida, California, and Texas, finding coverage at all has become a challenge.
“Insurance is no longer a ‘set it and forget it’ bill. The loyalty penalty is real—staying with the same carrier for a decade often means you are overpaying significantly compared to new customers.” — Industry analysis
Actionable Steps to Lower Premiums
Bundle Aggressively: Ensure your auto and home policies are with the same carrier. This remains the single easiest way to drop premiums by 15–20%.
Raise Your Deductible: Raising your deductible from $500 to $2,500 can lower your annual premium by hundreds of dollars. Just ensure you have that $2,500 set aside in an emergency fund.
Audit Your Coverage: Check if you are paying for “dwelling coverage” that far exceeds the replacement cost of your home. Land value should not be included in your dwelling coverage amount.
4. Streaming Services
The era of “cheap cord-cutting” is officially over. 2026 is being called the year of “Streamflation.” Major services like Paramount+, Disney+, and others have announced or implemented price hikes ranging from $1 to $3 per month.
While a few dollars might seem negligible, the average household now subscribes to four different services. A $2 increase across four apps adds nearly $100 to your annual expenses—money that could pay for two weeks of groceries.
| Service Type | Estimated Monthly Cost | Annual Impact |
|---|---|---|
| Ad-Free Premium (Single) | $15 – $23 | $180 – $276 |
| Ad-Supported (Single) | $8 – $10 | $96 – $120 |
| Typical Bundle (3 Services) | $45+ | $540+ |
How to Cut Costs
- Rotate Subscriptions: You don’t need Netflix, Hulu, and Max simultaneously. Subscribe to one, watch the shows you want, cancel it, and switch to the next.
- Check Your Cell Plan: Carriers like T-Mobile, Verizon, and AT&T often include free streaming subscriptions with their 55+ or unlimited plans. Verify you aren’t paying for something you already get for free.
- Accept Ads: Downgrading to ad-supported tiers can cut your bill in half. For many retirees, a 90-second commercial break is a fair trade for saving $120 a year.
5. Smartphones & Electronics
If you were planning to upgrade your iPhone or Android device this year, you might experience sticker shock. A combination of AI technology integration and memory chip shortages is pushing prices up. Analysts predict smartphone prices could rise by approximately 7% in 2026.
The demand for advanced chips to power Artificial Intelligence features is creating a bottleneck, and manufacturers are passing those costs on to consumers. Computers and tablets are expected to see similar price bumps of 15–20% in some categories.
The “Good Enough” Strategy
Unless you need the absolute latest AI features, buy last year’s model. The technology gap between a 2025 and 2026 phone is often minimal for standard users (calls, texts, photos, apps). Refurbished electronics from certified sellers (like Apple Refurbished, Amazon Renewed, or Best Buy Outlet) also offer essentially new devices with warranties for 20–30% less.
6. Electricity & Utilities
Keeping the lights on and the house cool will cost more this year. Wholesale electricity prices have been trending upward due to grid modernization costs and high demand. Projections indicate residential electricity bills could rise by roughly 3% to 12% in 2026 depending on your region.
This hits retirees particularly hard, as you likely spend more time at home than working-age adults.
Energy-Saving Wins
Phantom Load: Unplug electronics you don’t use daily. Cable boxes, game consoles, and older TVs draw power even when off.
Time-of-Use Plans: Check if your utility company offers “Time-of-Use” pricing. Running your dishwasher or laundry during off-peak hours (usually mornings or late nights) can be significantly cheaper than running them at 5:00 PM.
Getting Expert Help
Sometimes, rising costs signal a need to revisit your broader financial plan. Consider speaking to a professional if:
- Your Medicare costs are eating into your savings: A SHIP (State Health Insurance Assistance Program) counselor can help you review your plan options for free.
- You can’t keep up with insurance premiums: An independent insurance broker can shop rates across dozens of companies, whereas a “captive” agent (like State Farm or Allstate) can only show you their own rates.
- You are consistently dipping into principal savings: A fee-only financial planner can help you restructure withdrawals to ensure your money lasts.
A Note on Postage
You may have heard rumors about stamp prices. The good news: The USPS announced no price increase for stamps in January 2026 (staying at $0.78). However, keep an eye out for July, as mid-year adjustments are common. Shipping packages via Priority Mail, however, did get more expensive in January.
Final Thoughts
Price increases are inevitable, but they don’t have to derail your retirement. By anticipating these specific hikes—from your morning coffee to your monthly premiums—you can adjust your budget proactively rather than reactively. Focus on the variables you can control: shopping for insurance, rotating streaming services, and optimizing your energy usage.
The information in this guide is meant for educational purposes. Your specific circumstances—including income, savings, health coverage, and goals—may require different approaches. When in doubt, consult a licensed professional.
Last updated: February 2026. Retirement benefits, tax laws, and healthcare costs change frequently—verify current details with official sources like Medicare.gov and the Bureau of Labor Statistics.