
You could be walking away from thousands of dollars in retirement income if you overlook Social Security divorced spouse benefits.
When your marriage ends, your connection to your ex-spouse’s earnings record doesn’t automatically disappear; yet many retirees mistakenly believe they forfeit these benefits once the divorce is finalized.
Understanding the exact requirements allows you to claim up to 50% of your former spouse’s full retirement age benefit without their involvement. Whether you are nearing age 62, working part-time, or adjusting your financial strategy after a separation, knowing how these specific rules apply is critical.
This article breaks down the essential 2026 Social Security regulations, eligibility criteria, and claiming strategies you need to maximize your monthly income.
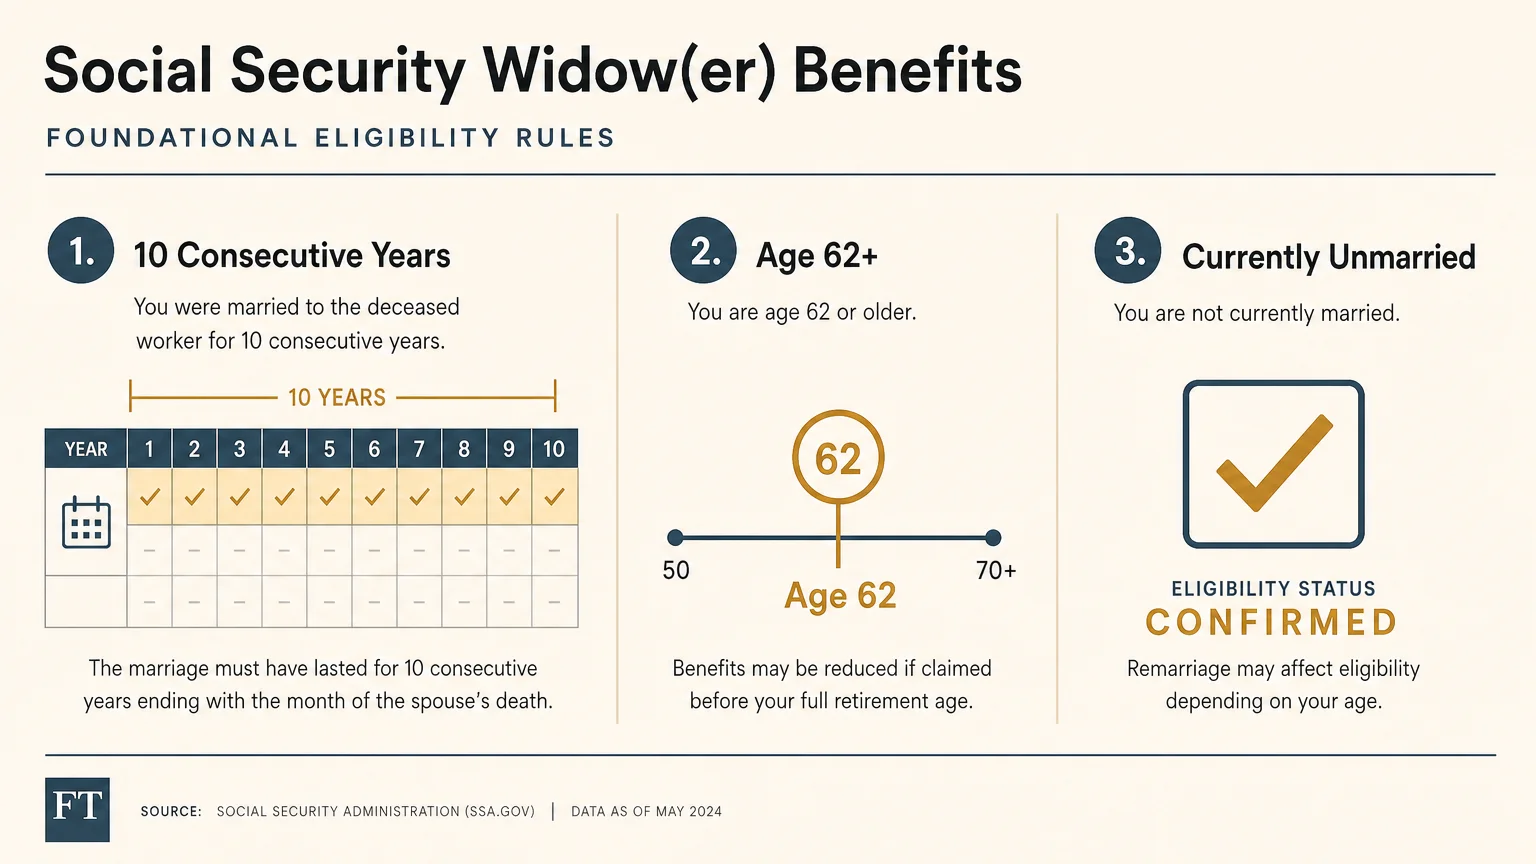
The 10-Year Rule and Foundational Eligibility
The Social Security Administration maintains strict criteria that govern whether you can legally claim benefits based on a former spouse’s earnings history. The primary hurdle most retirees face is the duration of the marriage. To qualify, you must have been married to your ex-spouse for a minimum of 10 consecutive years before the divorce became final. If your marriage lasted nine years and eleven months, you are unfortunately ineligible for this specific benefit class.
Assuming you meet the 10-year requirement, several other conditions must align for you to draw a divorced spousal benefit in 2026:
- Age requirement: You must be at least 62 years old to initiate a claim for standard spousal benefits.
- Current marital status: You must be currently unmarried. If you remarry, you forfeit your ability to collect benefits on your ex-spouse’s record unless your subsequent marriage ends through death, divorce, or annulment.
- Your ex-spouse’s entitlement: Your former spouse must be entitled to Social Security retirement or disability benefits.
- Your independent earnings record: Social Security will only pay you the divorced spouse benefit if it is higher than the benefit you would receive based on your own work history. You cannot stack the benefits; the government pays an amount equal to the higher of the two.
A common friction point for divorced retirees is the belief that their ex-spouse must actually be receiving checks for the spousal benefit to activate. This is not entirely true. If your ex-spouse qualifies for benefits but has delayed claiming them, you can still file for your divorced spouse benefits provided you have been legally divorced for at least two consecutive years.

Once you want to claim your own benefits..can you stop 1/2 payment from your ex & start your own since it is higher?
The increase is only your benefit amount or his. Whichever is the higher. No stacking of yours & some of his. Men usually earn more then a woman. You are entitled to the higher amount & it doesn’t affect his monthly amount he gets. Call the SS administration. This is something I’ve known about since I was in my 40’s, it’s unfortunate that SS keeps it quiet. You are entitled to his monthly amount, instead of yours, if his is higher.
Could depend if you were in a common law state. Call SS admi to find out
Call SS & find out
No. Just your own benefits. Gotta have 10 yrs of marriage to collect off of a spouse
Not some of his. It’s about if his amount would be higher then yours, you could draw his higher amount. Not your own. And it doesn’t affect his monthly amount either.
What benefits am I entitled to if i divorced my husband after 10 years then remarry at 32 years, both spouses die. I am 77 years old
I wasn’t married for ten years can I claim anything?
I lived with my spouse for 40 years but we never married, am I entitled to anything??
Suppose my Ex got married again?