Retired in USA

Your golden years are your best years! Make them shine!

  • Home
  • Personal Finance
  • Retirement Life
  • Saving & Spending

The Ultimate Pre-Retirement Checklist: Everything to Do in the 5 Years Before You Retire

August 25, 2025 · Personal Finance

Photo-realistic, senior-friendly scene that visually introduces the section titled '3 Years Out: Deep Dive into Income and Healthcare'.

3 Years Out: Deep Dive into Income and Healthcare

Three years from your target date, the picture of your retired life starts coming into sharper focus. This is the year to move from estimates to specifics, especially when it comes to your two biggest challenges: creating a reliable “paycheck” and preparing for healthcare costs.

Part 1: The Income Plan

Your goal is to replace your work paycheck with a retirement paycheck. This income will likely come from several sources, and your job is to figure out how they all fit together. Start by mapping out your guaranteed income streams.

First, get your official Social Security estimate. You can create a secure account on the Social Security Administration’s website, SSA.gov, to see your full earnings history and get a personalized estimate of your benefits at different claiming ages (such as 62, your full retirement age, and 70).

Next, if you are fortunate enough to have a pension, contact your employer’s HR department for a formal estimate of your monthly payout. Ask about your options, such as single-life versus joint-and-survivor payouts.

Now, let’s build a simple income ladder. This is a way to visualize how your essential bills get paid. Let’s look at a mini-example. Imagine your essential, fixed expenses in retirement (housing, food, utilities, insurance) total $3,500 per month. Your Social Security benefit at your chosen claiming age will be $2,200 per month, and your spouse’s will be $1,100. Together, that’s $3,300. This means you are only $200 short of covering all your essential needs with guaranteed income. You could choose to cover that small gap with a withdrawal from your savings or perhaps by purchasing a small annuity that pays out $200 a month for life. This strategy ensures your basic needs are met no matter what the stock market does, freeing up your investment portfolio to cover your variable lifestyle expenses.

Annuities can be a useful tool, but they must be approached with caution. An annuity is an insurance product that you buy with a lump sum of money in exchange for a guaranteed stream of income, often for the rest of your life. They can provide great peace of mind but often come with high fees, complex terms, and surrender charges (penalties for withdrawing your money early). Some have optional features called riders that can provide extra benefits, like income that increases with inflation, but these add to the cost. If you explore annuities, make sure you work with a trusted professional and read the contract carefully. You can learn more about investing principles from government sources like Investor.gov.

Part 2: The Healthcare Plan

Healthcare is one of the biggest and most unpredictable expenses in retirement. At the three-year mark, your priority is education. Medicare is the federal health insurance program for people 65 and older. It has several parts, and enrollment is not always automatic.

Your Initial Enrollment Period for Medicare typically begins three months before your 65th birthday and ends three months after. It is crucial to sign up during this window to avoid potential late-enrollment penalties that can last for the rest of your life. You can find all the official details and timelines at the official U.S. government site for Medicare, Medicare.gov.

You’ll need to make a key choice. You can go with Original Medicare (Part A for hospitals and Part B for doctors), often paired with a separate Part D plan for prescription drugs and a private Medigap policy to cover costs that Medicare doesn’t. Or, you can choose a Medicare Advantage plan (Part C), which is an all-in-one alternative offered by private insurers that bundles these coverages, often with extra benefits like dental and vision.

Finally, consider the possibility of long-term care. This refers to services that help with daily living activities, like bathing and dressing, which Medicare generally does not cover. Long-term care can be very expensive. Some people choose to buy long-term care insurance, while others plan to “self-insure” by setting aside a portion of their assets. This is a deeply personal decision that requires careful thought about your health, family situation, and financial resources.
Pages: 1 2 3 4 5 6 7 8 9 10

Share this article

Facebook Twitter Pinterest LinkedIn Email

Leave a Reply Cancel reply

Your email address will not be published. Required fields are marked *

Search

Latest Posts

  • Senior woman browsing fresh flowers at an outdoor street market with striped vendor tents and shoppers. Top 7 Retirement Destinations for Independent Seniors
  • Seniors walk along a landscaped stone courtyard outside a modern multi-story residential building near a water fountain. 10 Signs You’ve Found a Retirement Community Worth Joining
  • Man standing by a curbside mailbox opening an Annual Notice of Change envelope on an autumn suburban street. 8 Things to Do the Week Medicare Open Enrollment Opens
  • Man kneeling in a suburban front yard planting autumn flowers in a garden bed beside a brick home. 12 Cities With Retirement Homes Under $250,000
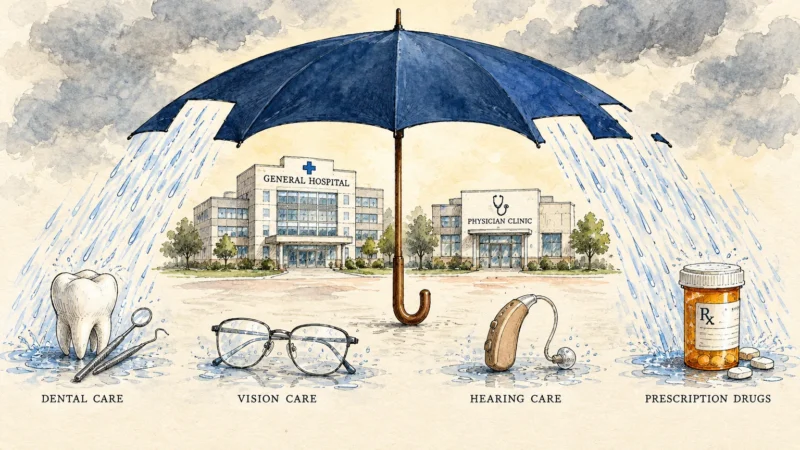
  • Illustration of a torn umbrella shielding a hospital and clinic while rain falls on dental, vision, and hearing items. 9 Things Original Medicare Doesn't Cover
  • Illustration split between busy city commuters on the left and a retired couple hiking along a sunny coastline on the right. 10 Spending Categories Where Retirees Say They Saved the Most
  • Senior man in an apron repairing a bicycle wheel mounted on a stand inside a sunlit workshop. 9 Ways Retirees Use Part-Time Income to Delay Withdrawals
  • Screenprint illustration of a small town square with a clock tower and gazebo, flanked by a beach and green mountains. 10 Cities Where $2,500 a Month Still Covers Everything
  • Older couple holding a large golden key to a stone archway overlooking a scenic coastal landscape. 10 Questions Couples Should Answer Before Filing Joint Retiree Taxes
  • Illustration of October, November, and December calendar pages floating toward a pocket watch above a bank vault. 8 Retirement Account Deadlines Hiding in the Last Quarter

Newsletter

Get retirement tips and senior living advice delivered to your inbox.

Related Articles

mistakes

7 Social Security Mistakes That Could Cost You a Fortune

Not checking your earnings record Did you know that the amount of benefits you will…

Read More →
An adult daughter and elderly mother sharing a happy moment in a bright, modern kitchen.

What Happens to Your Taxes When Mom or Dad Moves In?

Discover the tax implications of moving an aging parent into your home, including how to…

Read More →
insurance

5 Must-Have Insurance Any Retiree Should Own

A smiling senior couple relaxes on a garden patio, using a tablet to explore options…

Read More →
An older woman stands thoughtfully on her porch on a crisp autumn morning, holding a warm mug.

The Exact Number of Americans Who Retire Each Day — And What It Means

Discover the exact number of Americans retiring daily during the Peak 65 wave and learn…

Read More →
An older couple sitting at a wooden kitchen table, collaboratively planning their budget with a notebook and a tablet showing a trend line.

The 2027 COLA Prediction Tracker: How to Watch the Numbers Before October’s Announcement

Track the 2027 Social Security COLA predictions and learn how inflation and rising Medicare premiums…

Read More →
An editorial gouache illustration of a scale tipped by a single dollar coin, representing the IRMAA threshold.

The Retirement Income Trap That Pushes You Into a Higher IRMAA Bracket

Learn how to avoid Medicare IRMAA surcharges, navigate income traps like RMDs and municipal bonds,…

Read More →
Illustration of a torn umbrella shielding a hospital and clinic while rain falls on dental, vision, and hearing items.

9 Things Original Medicare Doesn’t Cover

Learn the 9 major healthcare services Original Medicare doesn't cover and discover actionable strategies to…

Read More →
A happy senior couple enjoying the view from their new modern apartment balcony at sunset.

How to Downsize Smartly: Selling the Family Home and What to Do With the Money

Learn smart strategies for downsizing your home in retirement, navigating capital gains taxes, and investing…

Read More →
A relaxed retired couple reviewing their financial plan on a laptop in a bright home office.

How to Avoid the Medicare IRMAA Surcharge (Income-Related Premium)

Learn exactly how the Medicare IRMAA surcharge is calculated, view the 2026 income brackets, and…

Read More →
Retired in USA

Your golden years are your best years! Make them shine!

Inedit Agency S.R.L.
Bucharest, Romania

contact@ineditagency.com

Trust & Legal

  • Contact
  • Editorial Policy
  • Advertiser Disclosure
  • FAQ
  • Subscribe
  • Unsubscribe
  • Privacy Policy
  • Terms and Conditions
  • Disclaimer
  • Do not sell my personal information
  • Request to Know
  • Request to Delete
  • CA Privacy Policy

Categories

  • Enjoying Retirement
  • Personal Finance
  • Saving & Spending

© 2026 Retired in USA. All rights reserved.