Retired in USA

Your golden years are your best years! Make them shine!

  • Home
  • Personal Finance
  • Retirement Life
  • Saving & Spending

New COLA Predictions Are In – Here’s What Retirees Should Know

June 22, 2026 · Personal Finance
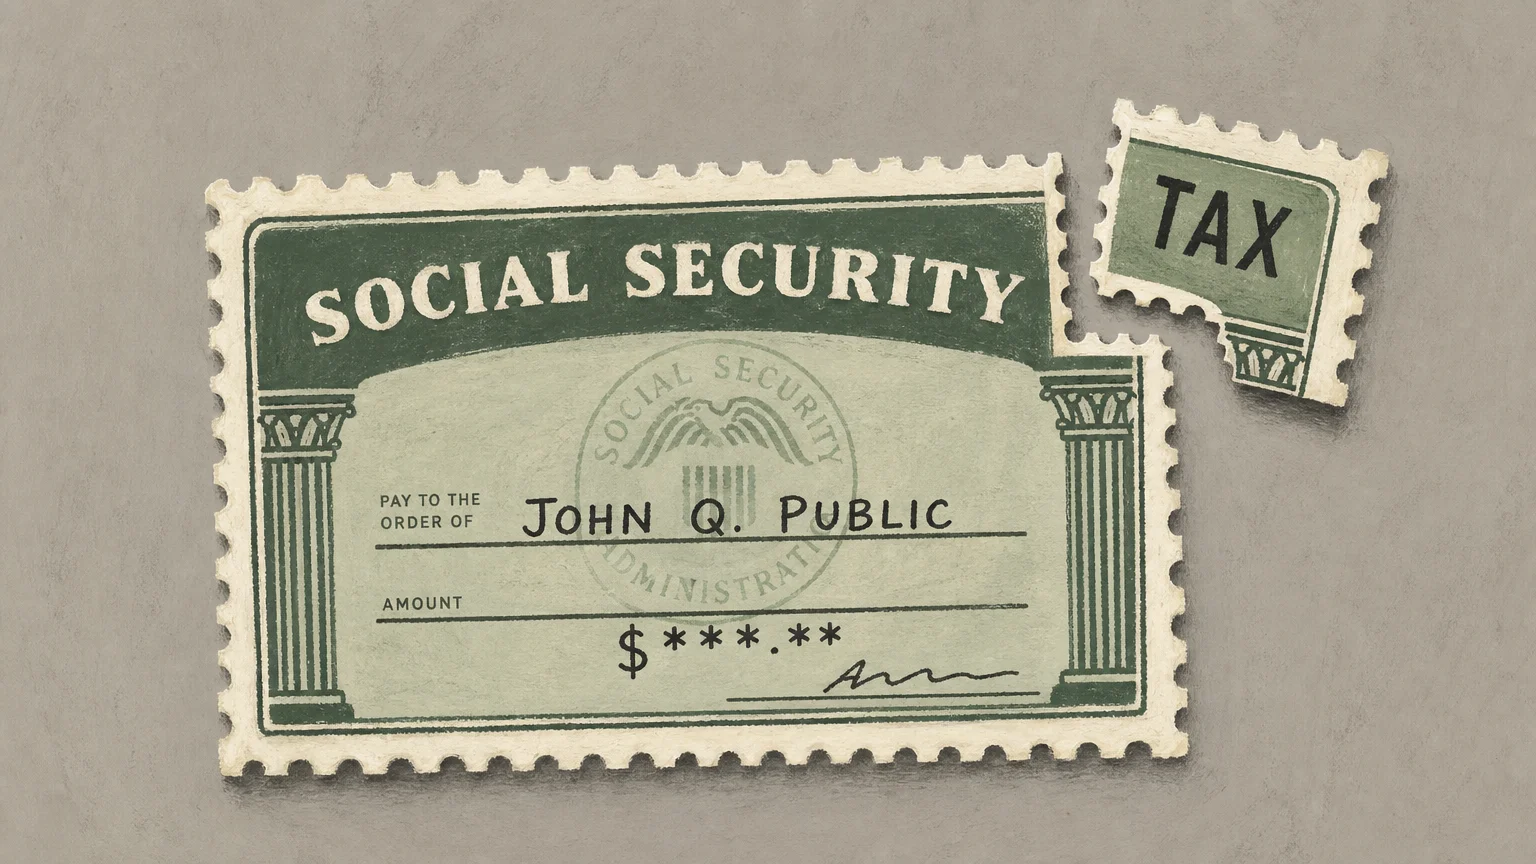
An editorial gouache illustration of a stylized stamp with a corner piece separated, symbolizing tax deductions on benefits.
A Social Security check with a torn tax corner illustrates how taxes impact your retirement benefits.

Taxes and Your Increased Benefits

One of the most persistent and frustrating surprises for new retirees is discovering that the federal government taxes Social Security benefits. What makes this taxation particularly aggressive during periods of high inflation is that the income thresholds triggering these taxes are not indexed for inflation. They have remained completely static since they were enacted decades ago.

The Internal Revenue Service uses a formula called “provisional income” (sometimes called combined income) to determine how much of your benefit faces taxation. You calculate your provisional income by taking your Adjusted Gross Income, adding any nontaxable interest (such as municipal bond interest), and then adding exactly 50 percent of your Social Security benefits.

If you file your taxes as an individual, a provisional income between $25,000 and $34,000 means up to 50 percent of your benefit may be taxable. If your provisional income exceeds $34,000, up to 85 percent of your benefit becomes taxable. For married couples filing jointly, the 50 percent threshold sits between $32,000 and $44,000, while incomes above $44,000 trigger the 85 percent taxation bracket.

Because these thresholds never change, a generous COLA acts as a double-edged sword. As your Social Security payments increase to keep pace with inflation, that extra income automatically drives up your provisional income. This phenomenon frequently pushes retirees over the $34,000 or $44,000 limits, subjecting a larger portion of their benefits to federal income tax. Managing this dynamic requires intentional tax planning.

As Ed Slott advises, proactive tax planning allows you to control your tax brackets. Many retirees execute strategic Roth conversions during years when their income dips, moving funds from tax-deferred IRAs into tax-free Roth IRAs. While you pay taxes on the converted amount today, any future withdrawals from that Roth IRA will not increase your provisional income. This strategy helps shield your future Social Security benefits from taxation, allowing you to keep more of your COLA.
Pages: 1 2 3 4 5 6 7 8 9 10

Share this article

Facebook Twitter Pinterest LinkedIn Email

Leave a Reply Cancel reply

Your email address will not be published. Required fields are marked *

20 comments on “New COLA Predictions Are In – Here’s What Retirees Should Know”

  1. Paul L Hevner says:
    September 28, 2026 at 5:47 pm

    3.8% COLA is a disgrace to those on SSI.
    You get a whopping extra $79 and medicare increases its monthly requirement.
    After that the $79 is shrunk down to if your lucky $10,.
    Quit wasting the money we put in from our salaries. and increase the COLA so we can keep up with inflation and not give it to Illegals…

    Depressed and frustrated senior citizen…………..

    Reply
  2. connie hughes says:
    September 22, 2026 at 7:47 am

    I’ll get about $154 more

    Reply
  3. Ryan Vitali says:
    September 21, 2026 at 4:35 pm

    COLA is so broken. The cost of gas has made almost a 20% increase and cost of food has nearly 30% increase on some items. 3% is not even a scratch on the surface. Its hard enough to get SSI but to work your whole life just to struggle because the government can’t do basic math is getting really old. COLA is suppose to reflect the Cost of Living. Ao if cost of living makes a 20% increase that year the SSI and VA Disability benefits should follow suit. Quit punishing the people who the government has lied to the longest.

    Reply
  4. William Brown says:
    September 14, 2026 at 1:49 pm

    Yeah, we appreciate everything we get, but this still is not enough for the older people

    Reply
  5. Robert Thompson says:
    August 22, 2026 at 9:59 pm

    The only good thing I have to say is I’m more and more grateful for the Blue Cross- Blue Shield insurance that, as a former VA employee, I carried over into retirement. Comparing BCBS with Medicare plan B, the latter is a ripoff.

    Reply
  6. Fred fierke says:
    August 22, 2026 at 6:51 pm

    3.8 per cent of nothing is still nothing

    Reply
  7. Randy says:
    August 16, 2026 at 5:20 pm

    Right on .They don’t get social security and the right wing lies about it to keep us divided by their ignorant base that don’t know any better since they are told to stay stupid and not research or think for themselves

    Reply
  8. Mary Betts says:
    August 12, 2026 at 1:46 am

    So we get a raise in social security but then Medicare raises its prices so SS is a very little increase. How about we make Congress paypack the monies they STOLE from Social Security and left WORTHLESS IOU’s in its place? Plus interest, it might make Social Security solvent. And then ahow about Congress has to pay into Social Security the way other people HAVE TO. How about any time they make a new rule, they have to follow it also and not be exempt! I’d be for all of that!

    Reply
  9. Mary says:
    August 12, 2026 at 12:26 am

    So we get a raise but Medicare immediately raises what they pull out. Your ‘raise’ is drastically reduced. How about we do 2 things: Make Congress pay back (with interest) the Worthless IOU’s they left when they Stole funds from Social Security. And make Congress pay into Social Security the way the people who work have to. Just a thought.

    Reply
  10. Mary says:
    August 12, 2026 at 12:20 am

    You get a bump in social security and Medicare immediately raises you costs so how much do you really realize in the SS gain? If they made Congress pay back all the WORTHLESS IOU’s they left when they stole monies from Social Security, it would put social security on solid financial ground. But they won’t pay it back yet keep raising their (Congress’) salaries ! And how about if Congress had to pay into social security instead of exempting themselves from it?

    Reply
Se încarcă comentarii...

Nu mai există comentarii de afișat.

Search

Latest Posts

  • An older man and a young female student holding a syllabus walk together along a sunlit college campus path. 12 Ways Grandparents Can Help Grandkids Save for College
  • Senior woman browsing fresh flowers at an outdoor street market with striped vendor tents and shoppers. Top 7 Retirement Destinations for Independent Seniors
  • Seniors walk along a landscaped stone courtyard outside a modern multi-story residential building near a water fountain. 10 Signs You’ve Found a Retirement Community Worth Joining
  • Man standing by a curbside mailbox opening an Annual Notice of Change envelope on an autumn suburban street. 8 Things to Do the Week Medicare Open Enrollment Opens
  • Man kneeling in a suburban front yard planting autumn flowers in a garden bed beside a brick home. 12 Cities With Retirement Homes Under $250,000
  • Illustration of a torn umbrella shielding a hospital and clinic while rain falls on dental, vision, and hearing items. 9 Things Original Medicare Doesn't Cover
  • Illustration split between busy city commuters on the left and a retired couple hiking along a sunny coastline on the right. 10 Spending Categories Where Retirees Say They Saved the Most
  • Senior man in an apron repairing a bicycle wheel mounted on a stand inside a sunlit workshop. 9 Ways Retirees Use Part-Time Income to Delay Withdrawals
  • Screenprint illustration of a small town square with a clock tower and gazebo, flanked by a beach and green mountains. 10 Cities Where $2,500 a Month Still Covers Everything
  • Older couple holding a large golden key to a stone archway overlooking a scenic coastal landscape. 10 Questions Couples Should Answer Before Filing Joint Retiree Taxes

Newsletter

Get retirement tips and senior living advice delivered to your inbox.

Related Articles

A retired school teacher in her late 60s sits thoughtfully in her sunlit kitchen, holding a warm ceramic mug in natural golden hour light.

The Government Pension Offset Rule Still Catching Retirees Off Guard

Discover how the Social Security Fairness Act repeals the Government Pension Offset, tax impacts of…

Read More →
An artistic mixed-media paper collage ranking ten layers from tax-free light green to highly-taxed dark rust.

10 Retirement Income Types Ranked by How They’re Actually Taxed

Discover how 10 common retirement income sources are actually taxed and learn how to structure…

Read More →
social security numbers

6 Social Security Changes Coming Next Year

#2 Full Retirement Age Reaches 67 For those born in 1960 or later, the Full…

Read More →
A senior couple laughs while packing a leather suitcase in a sunlit bedroom, symbolizing newfound financial freedom.

8 Signs You No Longer Need the Life Insurance Policy You’ve Kept for Decades

Discover 8 clear signs you no longer need life insurance in retirement and learn actionable…

Read More →
401k Loan

401k Loans: Are They REALLY Worth It?

Benefit: Convenience And Speed In most 401k plans, requesting a loan is easy and fast…

Read More →
spousal

How Can You Increase Social Security with Spousal Benefits?

How much you should expect for spousal Social Security benefits Your spousal benefit will turn…

Read More →
Savings

10 Huge Mistakes That Will Drain Your Savings

A man examines a financial app on his smartphone, illustrating the need to monitor spending…

Read More →
A conceptual mid-century style illustration of a retiree building a shield from planks labeled with financial strategies against a windy bac

5 Ways to Build Your Own COLA Now If You’re Worried About a Smaller Social Security Raise in 2027

Protect your retirement income from rising costs and Medicare premium hikes by building a personalized…

Read More →
A confident retiree working on a tablet in a bright, modern home office during the morning.

Best Jobs for Retirees in 2026

Explore the best flexible and high-paying jobs for retirees in 2026. Get current data on…

Read More →
Retired in USA

Your golden years are your best years! Make them shine!

Inedit Agency S.R.L.
Bucharest, Romania

contact@ineditagency.com

Trust & Legal

  • Contact
  • Editorial Policy
  • Advertiser Disclosure
  • FAQ
  • Subscribe
  • Unsubscribe
  • Privacy Policy
  • Terms and Conditions
  • Disclaimer
  • Do not sell my personal information
  • Request to Know
  • Request to Delete
  • CA Privacy Policy

Categories

  • Enjoying Retirement
  • Personal Finance
  • Saving & Spending

© 2026 Retired in USA. All rights reserved.