
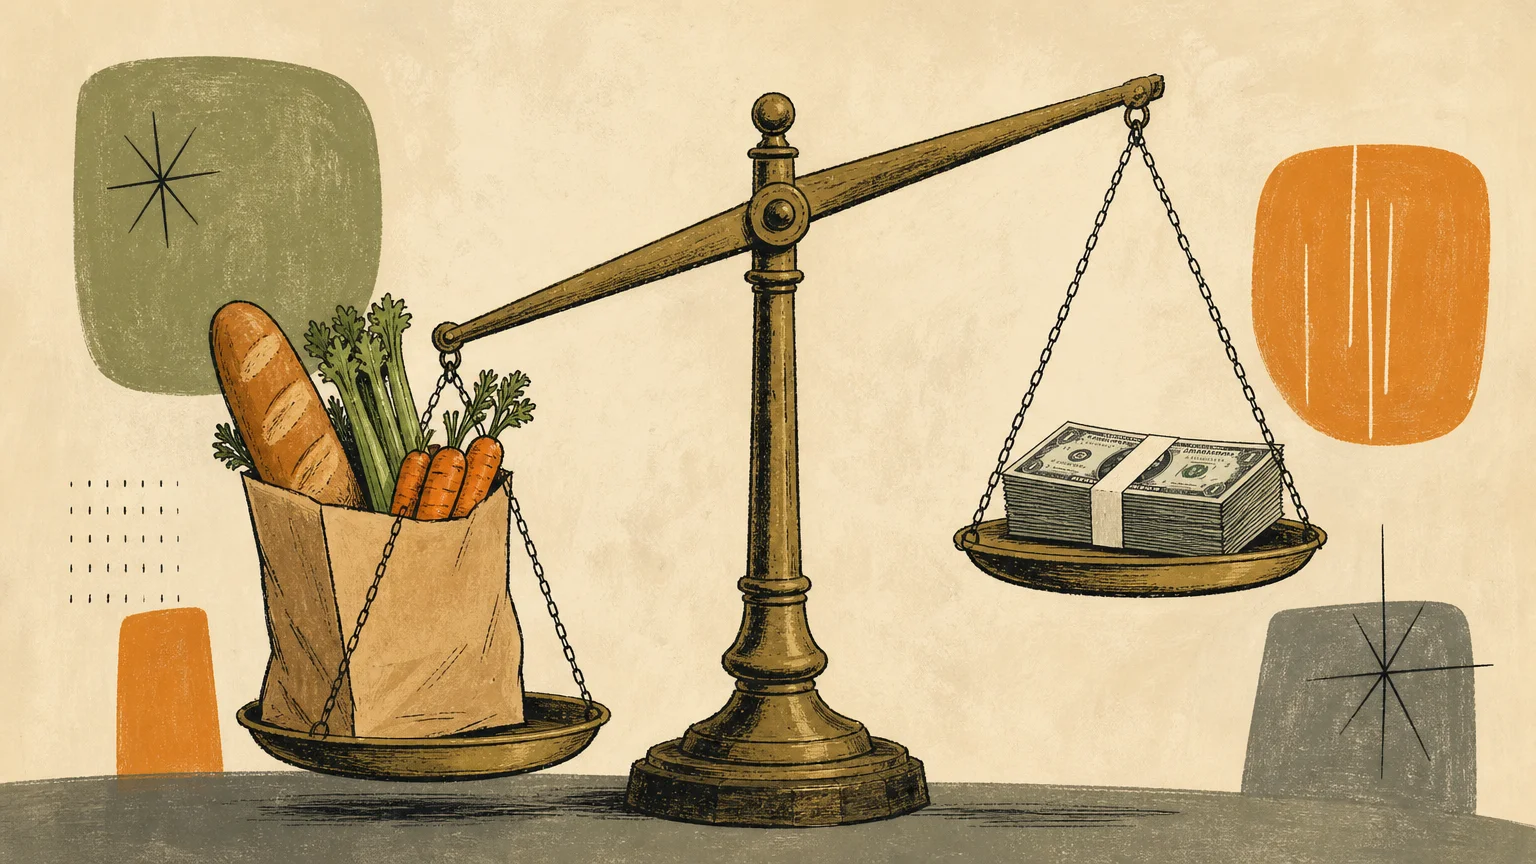
Navigating the Purchasing Power Gap
The core purpose of the cost-of-living adjustment is to preserve your purchasing power. It is not a raise or a bonus; it is a defensive mechanism designed to prevent inflation from eroding your standard of living. However, many retirees find that their personal rate of inflation runs much higher than the official national average.
This discrepancy happens because retirees spend their money differently than the general population. While younger workers might allocate a large percentage of their income to transportation, apparel, and electronics, older adults spend a disproportionate amount of their budget on healthcare, prescription drugs, housing, and groceries. When the prices for these specific categories surge, a standard COLA often feels inadequate.
Bridging this purchasing power gap requires you to re-evaluate your withdrawal strategy. If your Social Security COLA fails to cover the rising cost of your specific expenses, you must pull more from your investment portfolio to maintain your lifestyle.
Relying on a rigid “4 percent rule” withdrawal strategy can be dangerous during high-inflation years. Instead, you need a flexible approach that allows you to trim discretionary spending while ensuring your essential needs remain fully funded.
I’ll get about $154 more
COLA is so broken. The cost of gas has made almost a 20% increase and cost of food has nearly 30% increase on some items. 3% is not even a scratch on the surface. Its hard enough to get SSI but to work your whole life just to struggle because the government can’t do basic math is getting really old. COLA is suppose to reflect the Cost of Living. Ao if cost of living makes a 20% increase that year the SSI and VA Disability benefits should follow suit. Quit punishing the people who the government has lied to the longest.
Yeah, we appreciate everything we get, but this still is not enough for the older people
The only good thing I have to say is I’m more and more grateful for the Blue Cross- Blue Shield insurance that, as a former VA employee, I carried over into retirement. Comparing BCBS with Medicare plan B, the latter is a ripoff.
3.8 per cent of nothing is still nothing
Right on .They don’t get social security and the right wing lies about it to keep us divided by their ignorant base that don’t know any better since they are told to stay stupid and not research or think for themselves
So we get a raise in social security but then Medicare raises its prices so SS is a very little increase. How about we make Congress paypack the monies they STOLE from Social Security and left WORTHLESS IOU’s in its place? Plus interest, it might make Social Security solvent. And then ahow about Congress has to pay into Social Security the way other people HAVE TO. How about any time they make a new rule, they have to follow it also and not be exempt! I’d be for all of that!
So we get a raise but Medicare immediately raises what they pull out. Your ‘raise’ is drastically reduced. How about we do 2 things: Make Congress pay back (with interest) the Worthless IOU’s they left when they Stole funds from Social Security. And make Congress pay into Social Security the way the people who work have to. Just a thought.
You get a bump in social security and Medicare immediately raises you costs so how much do you really realize in the SS gain? If they made Congress pay back all the WORTHLESS IOU’s they left when they stole monies from Social Security, it would put social security on solid financial ground. But they won’t pay it back yet keep raising their (Congress’) salaries ! And how about if Congress had to pay into social security instead of exempting themselves from it?
retired people continue to get screwed. the lying piece of shit government knows inflation is well above 10 percent but they continue to stick it to us.